Use Year-End Tax Incentives to Lower the Cost of a Yale Forklift
December puts two clocks on the same desk. One is the warehouse clock: trailers to unload, lines to feed, yards to keep moving. The other is the tax clock. For most calendar-year businesses, that second clock stops on December 31.
If a Yale lift truck was already on your 2026 list, those two clocks can work together. Year-end tax incentives can reduce the after-tax cost of a qualifying purchase, as long as the truck is placed in service (ready and available for business use) before the year closes. A signed quote in December with a January delivery generally belongs on the 2027 return.
Black Equipment is an authorized Yale dealer. We help warehouses, 3PLs (third-party logistics providers), manufacturers, and outdoor yards across Indiana, Kentucky, Tennessee, Arkansas, and Illinois line up the right truck with a deadline that is still realistic.
This post covers the 2026 rules at a planning level, then shows how they show up on the kinds of Yale equipment our customers actually run.
What to take away first
- December 31, 2026 is the practical cutoff for a 2026 deduction if you file on a calendar year.
- Yale forklifts and related material handling equipment often qualify when business use is more than 50 percent.
- For tax years beginning in 2026, Section 179 (the election to deduct qualifying equipment in the year you place it in service) can cover up to $2,560,000, with a phase-out that starts above $4,090,000.
- 100 percent bonus depreciation (an extra first-year write-off that can apply after Section 179) is generally available for qualifying property acquired and placed in service after January 19, 2025.
- New and used Yale trucks can both qualify. Financed units can too.
- Buy the application first. Use the tax calendar second. Your CPA should confirm what you can claim.
Year end is when a delayed truck starts costing more than the payment
Once 2026 closes, you cannot pull that purchase back onto this year’s return. What you can still do, in March, is live with the unit you did not replace.
Yale pallet stackers deliver exactly that kind of focused performance. These electric walkie stacker models excel at lifting and stacking pallets where larger equipment would struggle with tight turns or limited room.
They offer a smart middle ground for many tasks, supporting better productivity and safety without the complexity or footprint of full-size forklifts. At Black Equipment, we see facilities across Kentucky, Indiana, Tennessee, and Arkansas turning to these solutions to stay competitive and keep goods moving smoothly.
That is the part operations feels first:
- A warehouse or 3PL truck that cannot keep dock-to-stock pace.
- A manufacturing unit that spends more hours waiting on parts than moving product.
- A yard truck that struggles in weather, ruts, or long outdoor runs.
A year-end Yale purchase is usually a readiness decision. The tax rules make the timing more attractive if the truck was already justified.
Section 179 and bonus depreciation, without the fog
Two federal tools do most of the work on tax savings for equipment purchases.
Section 179 lets an eligible business expense qualifying property in the year it is placed in service, instead of spreading the cost across a multi-year depreciation schedule (the normal write-off of an asset’s cost over its useful life). For 2026 the maximum Section 179 deduction is $2,560,000. It shrinks dollar for dollar once total qualifying property placed in service exceeds $4,090,000, and it is gone at $6,650,000.
The deduction cannot take business taxable income below zero. Unused amounts can often be carried forward.
Bonus depreciation can then apply to remaining qualifying basis. For property acquired and placed in service after January 19, 2025, the rate is generally 100 percent. There is no Section 179-style dollar cap, and bonus depreciation can create or increase a net operating loss.
Points we hear every December in our branches:
- The IRS cares that the asset is in service, not that you paid cash.
- Business use generally needs to be more than 50 percent. The deduction follows that percentage.
- You claim the election on IRS Form 4562 with the return.
- These are federal rules. States do not all follow them the same way.
Treat the figures here as planning context. Limits and eligibility can change, and your facts control the result.
What this looks like on a Yale fleet
You do not need a rare model to use these rules. Most year-end conversations in our territory land on workhorse series and a power choice that fits the site.
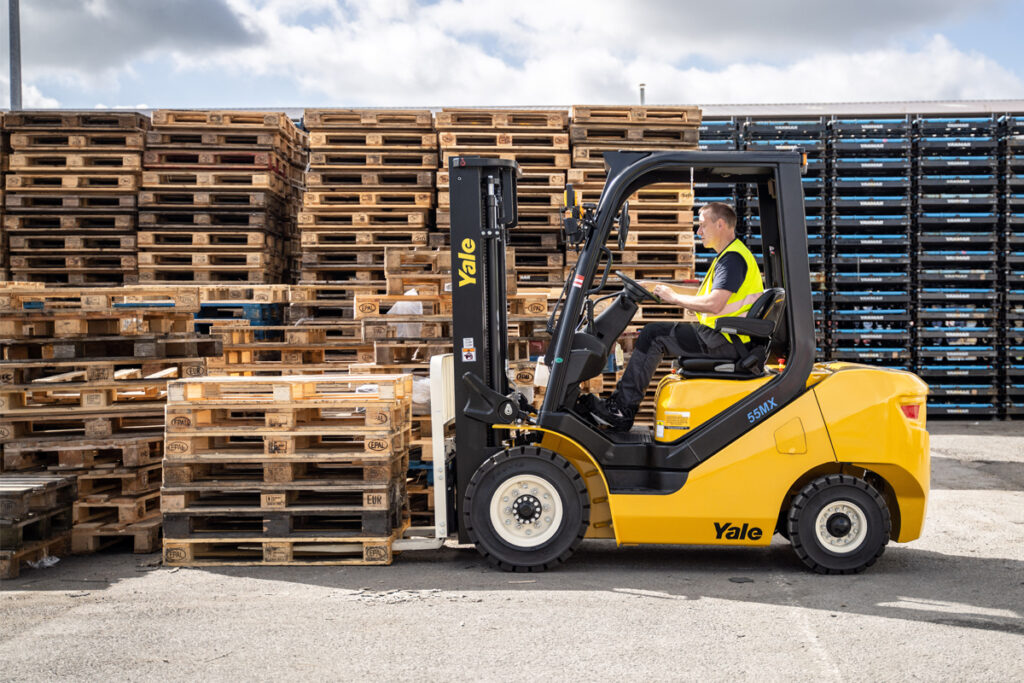
Warehouse and 3PL floors often look at Yale ERC-VG cushion-tire electric sit-down trucks in the 4,500 to 7,000 lb range, or Yale ESC three-wheel stand-up electrics in the 3,000 to 4,000 lb range for trailer and tight-dock work. Order picking and narrow-aisle work may point to Yale OS, SS, or FS series pickers around 3,000 lb.
Manufacturing plants mix indoor electrics with heavier capacity. A mid-range ERC-VG or ERP four-wheel electric still covers a lot of in-plant moves. When loads step up, Yale high-capacity electric series such as ERP-VNL (about 15,500 to 19,000 lb with integrated lithium-ion) come into the conversation.
Outdoor yards, lumber, building materials, and mixed indoor-outdoor routes still lean hard on Yale GP-VX pneumatic ICE (internal combustion engine) trucks, commonly in the 4,000 to 8,000 lb band, with LPG a frequent fuel choice. That demand has not faded. At the same time, more customers are moving the same kind of work onto battery power, including factory-integrated lithium-ion on series such as ERC-VGL (about 5,000 to 6,000 lb) and the higher-capacity ERP-VNL range.
In our market, LPG and battery are running about even. Lithium-ion is the transition story on the electric side. Lead-acid is still in the mix where the charging room and duty cycle already work. The tax code generally does not pick a winner among those power sources. If the truck is qualifying business property and it is placed in service in time, the incentive conversation can proceed. The operating conversation is separate: charging infrastructure, fuel logistics, maintenance hours, and multi-shift runtime.
How the deduction shows up in cash, not just on a form
Standard depreciation recovers cost slowly. Section 179 can put much or all of a qualifying Yale truck on this year’s return, which can lower taxable income now.
A simplified illustration, not a tax calculation: a mid-capacity Yale electric in the 5,000 lb class is placed in service in 2026 at $55,000. If your business can use a $55,000 deduction and sits in a 21 percent federal bracket, federal tax drops by about $11,550. Entity type, other purchases, bonus depreciation elections, state tax, and the taxable-income limit all change that number. Black Equipment can help you compare configurations. Your advisor files the position.
That first-year write-off also changes quote comparisons. A lithium-ion package or a heavier mast can look steep on the purchase order and closer after tax, if it cuts downtime. That is the capital equipment tax advantage worth running before you freeze a spec.
Start with the work. Then use the calendar.
Tax savings do not fix the wrong truck.
Before anyone talks December 31, walk the floor or the yard:
- Which units have rising repair tickets or long parts waits?
- Are attachments still matched to the product mix?
- Is the bottleneck a sit-down counterbalance, a stand-up dock truck, or an outdoor pneumatic?
- Is the next truck LPG, lead-acid, or lithium-ion, given how you fuel or charge today?
Replacing a tired Yale that is already limiting throughput is a clean case for a year-end forklift investment. Buying a spare because the tax year is ending is not. Capacity, tire type, mast, and power source still decide whether the savings last.
Promotions, lead times, and the date that actually counts
Year-end dealer offers can cut the purchase price. Tax incentives then apply to the basis you actually have after discounts and any other adjustments your advisor identifies.
Both clocks have to clear:
- The promotional price still has to be available.
- The truck has to be delivered, set up, and ready for use before year end.
A Yale unit already in our inventory can often be placed in service in days. A factory-configured truck ordered in mid-December may not make December 31. Lithium-ion packages can add charger and infrastructure lead time. LPG units are simpler on fueling, but they still need delivery, commissioning, and paperwork.
Ask for total cost of ownership (purchase price plus energy or fuel, maintenance, downtime, and tax effect), not just a monthly payment.
Where Black Equipment fits, and where we stop
Dealer supported purchase planning is useful when it stays in its lane.
We can:
- Match warehouse, 3PL, manufacturing, and yard applications to Yale series that commonly qualify.
- Check stock and factory slots against a December placed-in-service goal.
- Coordinate delivery, commissioning, and the documents your files will want.
- Talk through new, used, and rental-to-purchase paths that still leave the asset eligible.
- Bring fleet data into the decision when you already run Premier Fleet or similar telematics.
We cannot give tax advice, guarantee a deduction, or complete Form 4562. That belongs with your CPA or tax attorney. Bring them in before the purchase order, not after the truck is on the dock.
Make the last quarter count
The sequence that works is short. Confirm the fleet need. Confirm the Yale series, capacity, and power source fit the work. Then use year-end tax incentives if the placed-in-service date is still honest.
If a replacement has been sitting on the list since summer, this is the window where operations and the tax calendar line up. Walk the units that are costing you time. Ask what Black Equipment can have working before December 31. Then have your advisor run Section 179 and bonus depreciation against your return.
Ready to look at Yale options that can still make a 2026 date? Start at blackequipment.com or contact your local Black Equipment branch. We will match available trucks to the application and the timeline. Your tax advisor should sign off before you finalize the buy.
Disclaimer: This article is general information for planning conversations. It is not tax, legal, or accounting advice. Section 179 limits, bonus depreciation rules, qualifying property tests, and state conformity can change and vary by taxpayer. Confirm current law and your specific facts with a qualified tax professional before you purchase or file. Yale is a registered trademark of its owner. Black Equipment is an authorized Yale dealer.
OR
Click for your local branch